



Yulia Pavliuk is a financial content writer with a background in language, education, and clear communication. She creates SEO-friendly articles that make complex finance topics like ETFs and forex signals clear and accessible, with a strong focus on UK audiences.
 Fact checked
Advertising Disclosure
We may receive compensation from our partners for placement of their products or services, which helps to maintain our site. We may also receive compensation if you click on certain links posted on our site. While compensation arrangements may affect the order, position or placement of product information, it doesn’t influence our assessment of those products.
When UK savers consider investing, shares and property often come to mind first. Bonds, however, remain underused despite offering a way to earn steady returns with less volatility than equities. During periods of rising interest rates or volatile stock prices, they can help reduce risk and provide regular income.
For beginners, understanding how bonds work, where to buy them, and the main risks is essential. This guide explains the basics so you can approach bond investing with clarity and confidence.
In This Guide
Top Brokers for Investing in Bonds
1. eToro

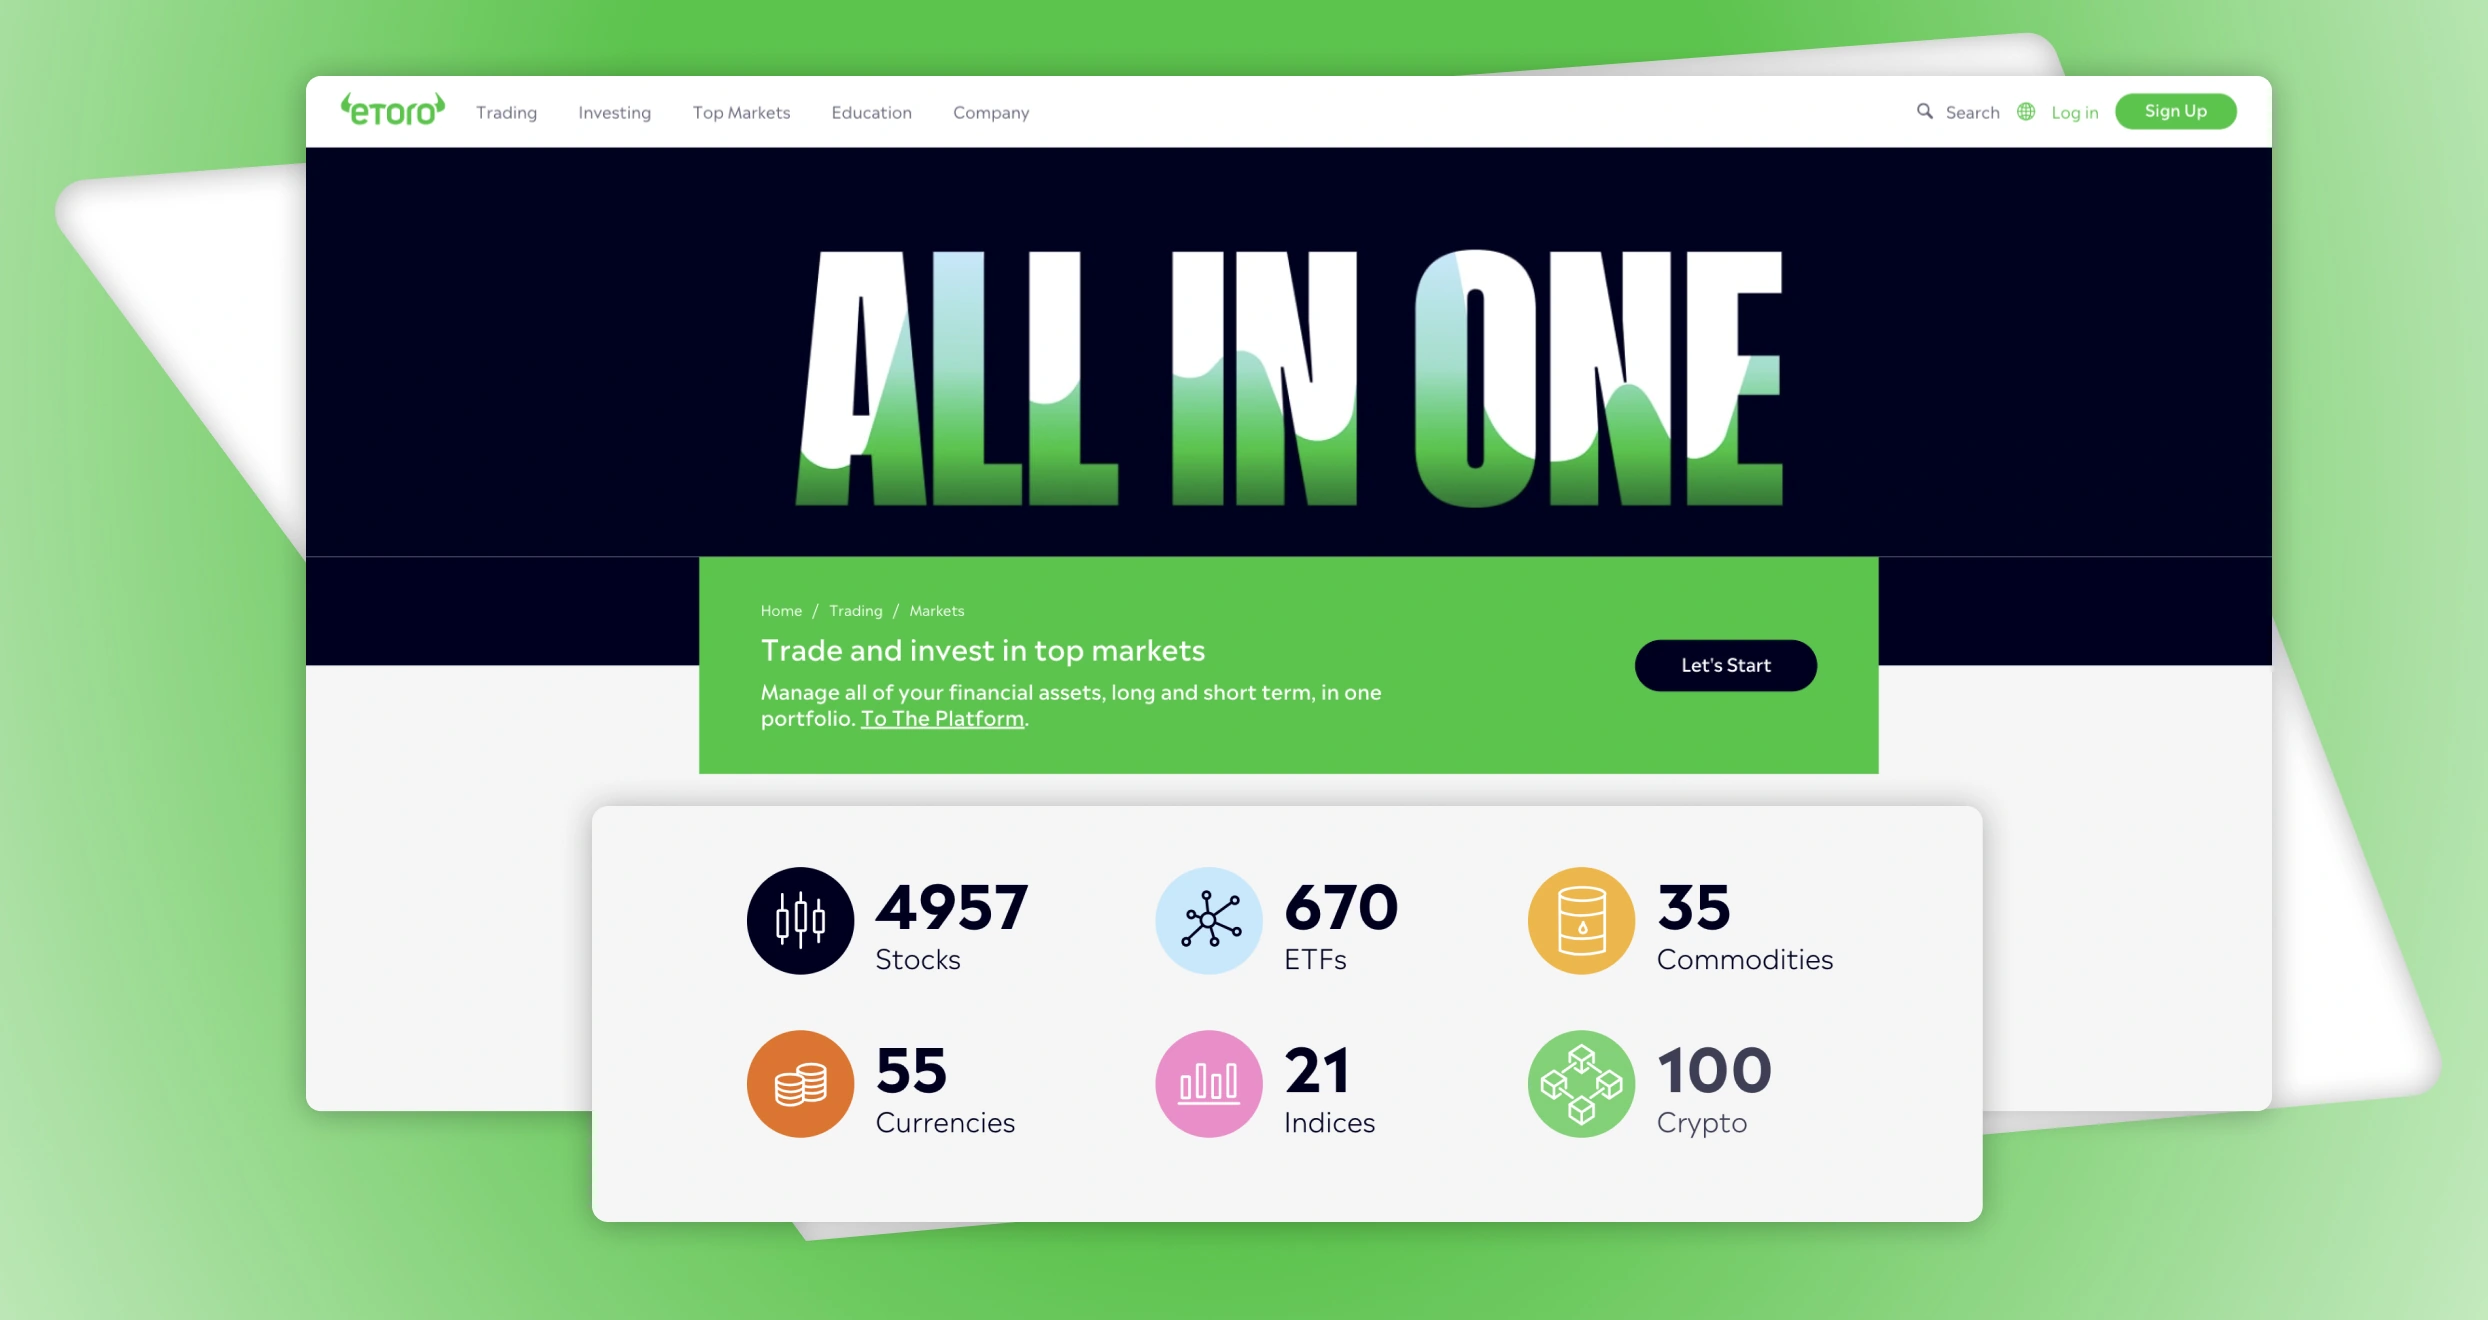
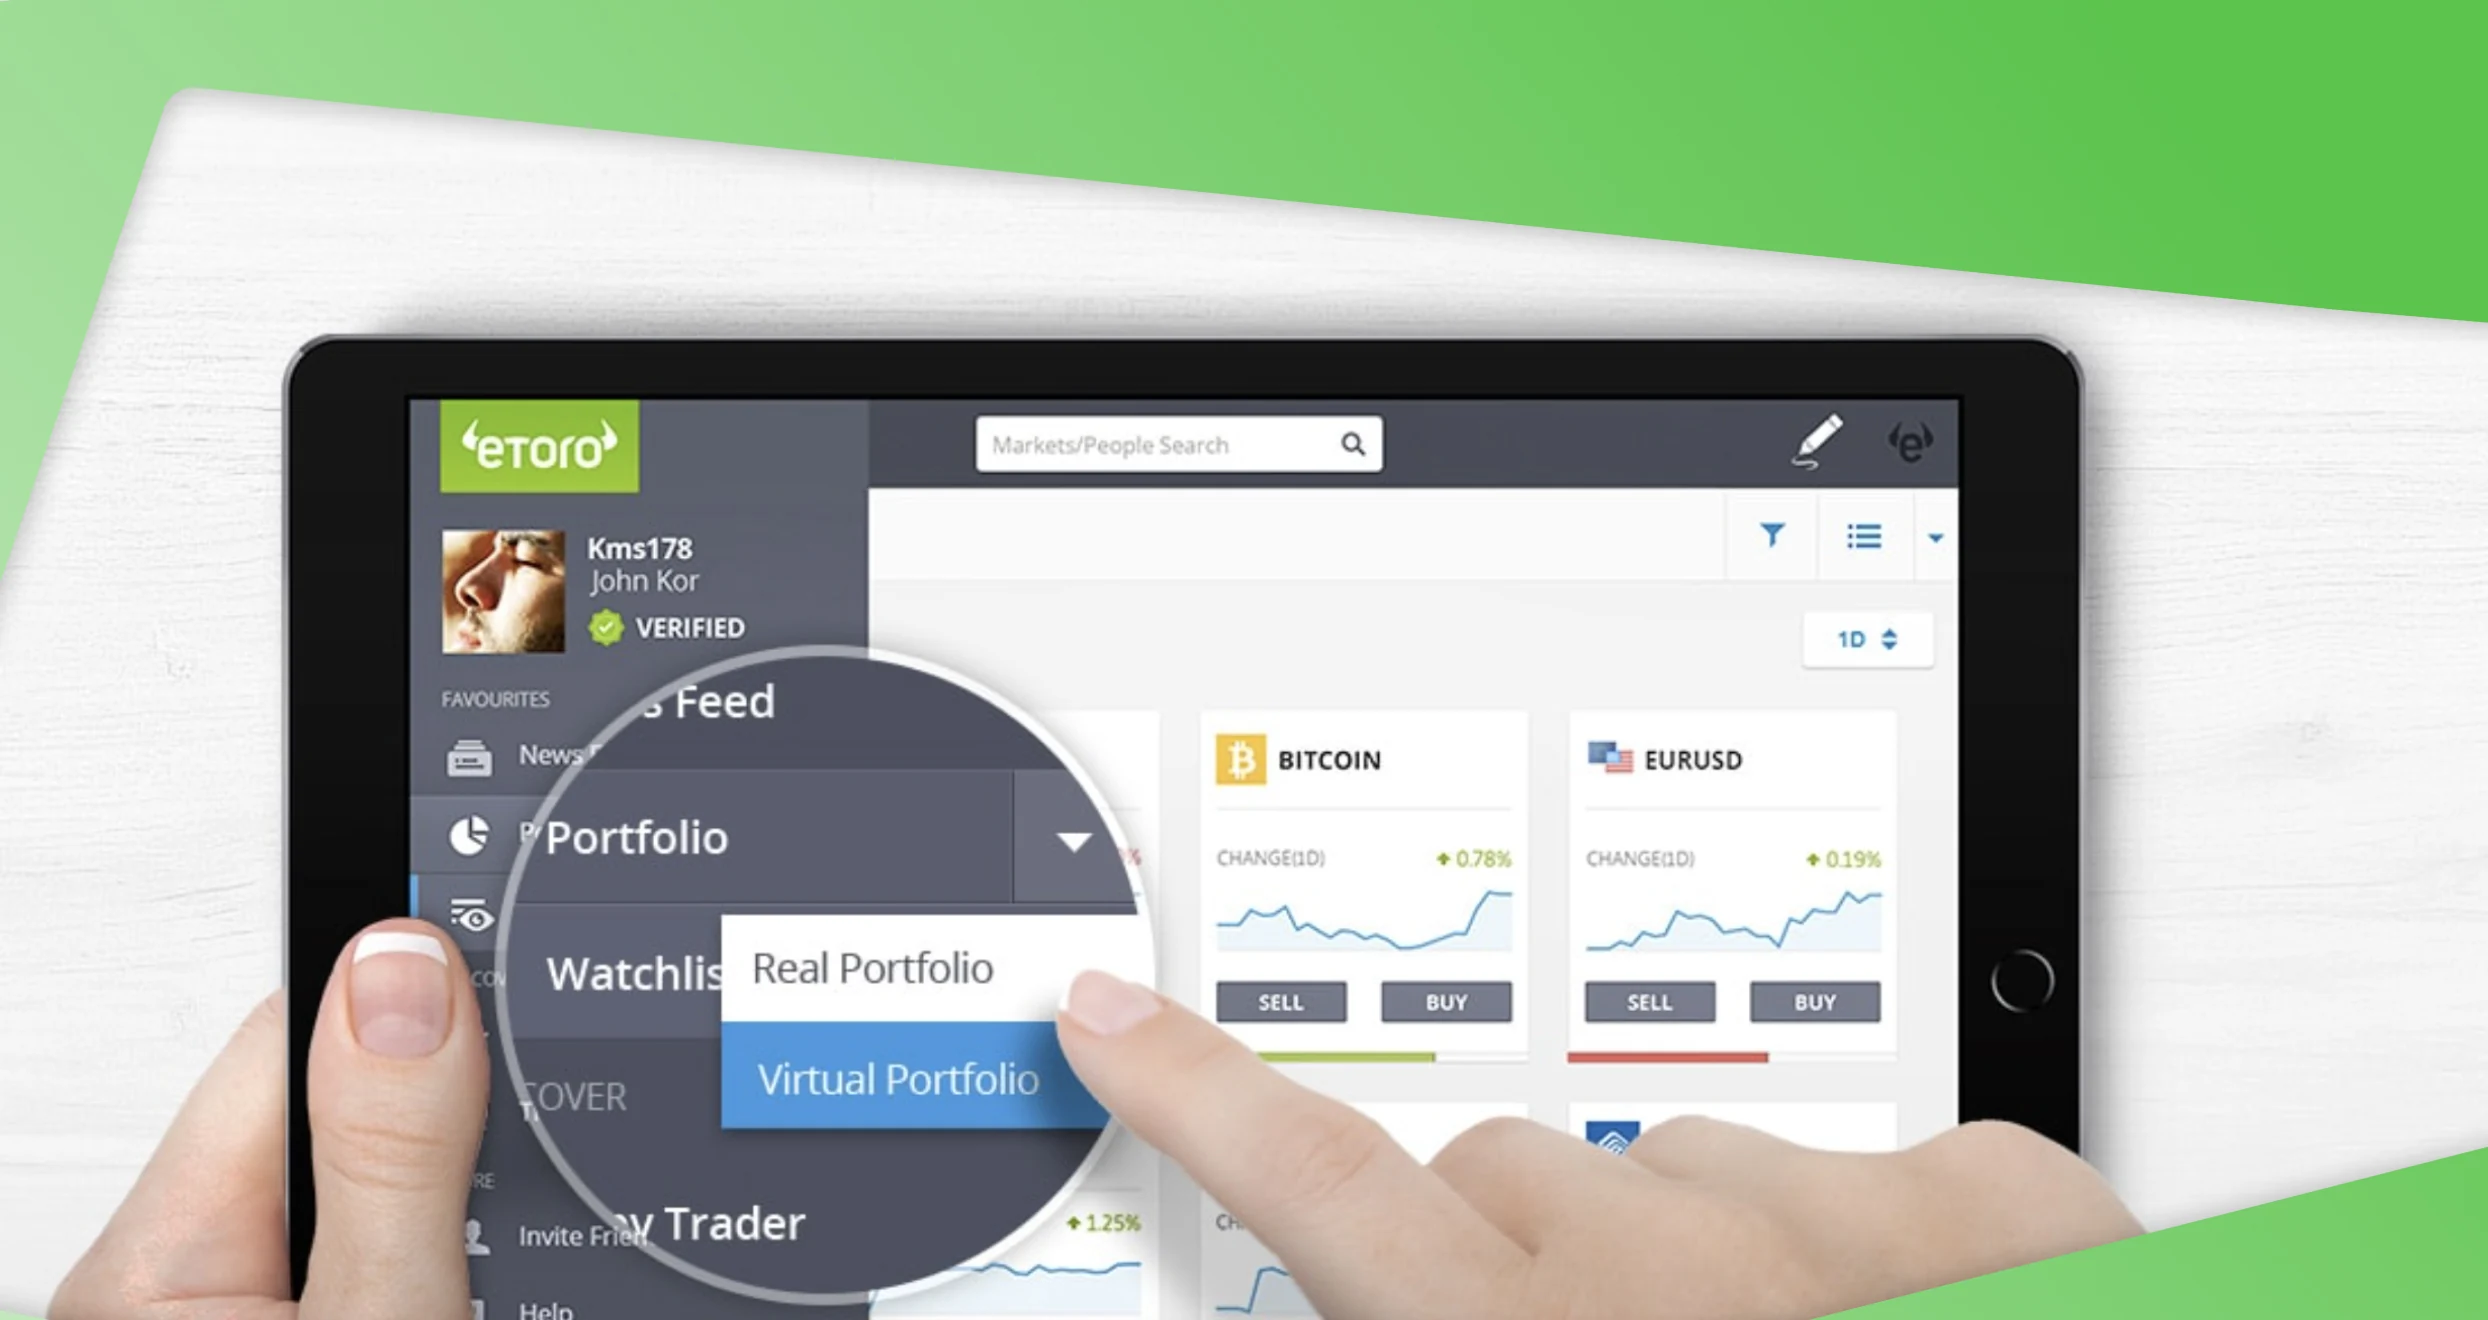

eToro doesn’t list individual government or corporate bonds. Instead, it offers CFD exposure to bond ETFs, such as those tracking short- and long-dated US Treasuries. You will be tracking the fund’s price rather than holding bonds directly. There are no commissions, and you only need £50 to get started.
Positions are opened through eToro’s web platform or app. Non-leveraged positions held for the long term avoid overnight financing charges, keeping the replication close to the underlying ETF’s actual performance. Besides bond ETFs, eToro is home to global stocks, forex, indices, commodities, and more.
eToro
✔5000+ financial instruments
✔Cost-free deposits
Pros & Cons
Fees
Trading Assets
Pros
- No overnight fee on non-leveraged bond ETF CFDs.
- Low minimum investment amount of £10.
- Low £50 minimum deposit requirement.
- Features social and copy trading.
Cons
- No individual bonds, ETF exposure only.
- £5 withdrawal fee from a USD wallet.
If there’s anything that can eat away at your profit margins, it’s unnecessary costs. Thankfully, eToro fees UK are reasonable and pocket-friendly. We acquired a new account without paying a single cent, which was quite a relief. We also noticed that you can enjoy free deposits by using USD. That said, eToro supports many other currencies, including GBP, EUR, and RMB.
You will incur conversion fees if you use any currency other than USD. And if you use any currency that eToro doesn’t support, you must pay conversion fees to your payment provider. The exact conversion fees you may incur at any moment will depend on various factors, including your preferred currency and payment method.
Please note that eToro subjects each withdrawal request to a £5 fee. The platform uses this money to pay expenses arising from international money transfers. Most importantly, you can’t withdraw less than £30 from the eToro trading platform.
While depositing money into our account, we noticed that eToro has strict minimum deposit requirements. Britons using this platform have to deposit at least £100 the first time. Afterwards, you can fund your account with as little as £10, depending on your preferred payment method.
Commission-wise, eToro is very friendly to people who trade ETFs or invest in real stocks since the broker charges 0% for these assets. On the other hand, if you buy or sell crypto on this platform, expect to pay a 1% fee. CFD trading also attracts variable spreads depending on the involved instruments. For instance, the spreads for currencies and commodities start from 1 pip and 2 pips, respectively.
Not to forget, eToro charges a £10 monthly inactivity fee that kicks in after 12 months of dormancy.
2. Pepperstone


Pepperstone offers CFDs on major sovereign bonds, including UK Gilts, US Treasuries across several maturities, and German Bunds, priced off the front-month futures contract. There’s no fixed minimum deposit, with £500 recommended as a working balance. Withdrawals are fee-free apart from international wires.
Bond CFDs trade through MT4, MT5, cTrader, or TradingView, giving access to charting tools suited to tracking rate-sensitive price moves. Because US bond futures trade almost around the clock, gapping risk is lower than with many other instruments
Pepperstone
✔24/7 customer support
✔No inactivity fees
Pros & Cons
Fees
Trading Assets
Pros
- Direct exposure to UK Gilts, US Treasuries, and Bunds.
- Lower gapping risk due to near-24hr bond futures trading.
- No minimum deposit.
- Lists an additional 2,700+ asset classes.
Cons
- CFD-only, no bond ownership or coupon income.
- Overnight financing on open positions.
After evaluating Pepperstone, we opened a trading account for conducting extensive tests. The process was quick and easy.
But what impressed us most was the Pepperstone minimum deposit requirement. This platform has no minimum deposit, which makes it ideal for low-budget and high-budget traders. If you are a beginner, joining this broker is advisable since you can start with a low amount and increase your stakes with time. To top it off, Pepperstone supports free deposits and withdrawals. This broker allows you to use diverse payment methods for free, from Visa debit and credit cards to PayPal and domestic bank transfers.
When it comes to spreads and commissions, Pepperstone is very cost-friendly. You can open a Razor account with this broker and enjoy 20 commission-free trades. Pepperstone’s Standard accounts also have zero commissions. On the other hand, spreads start from as low as 0.0 pips for forex pairs like EUR/USD and 0.5 for commodities like XAUUSD.
Finally, unlike most of its peers, Pepperstone charges zero inactivity fees. However, any positions you hold overnight with this platform are subject to swap rates. Visit Pepperstone’s pricing page for a detailed account of how this broker calculated swap rates for different financial instruments.
3. Capital.com
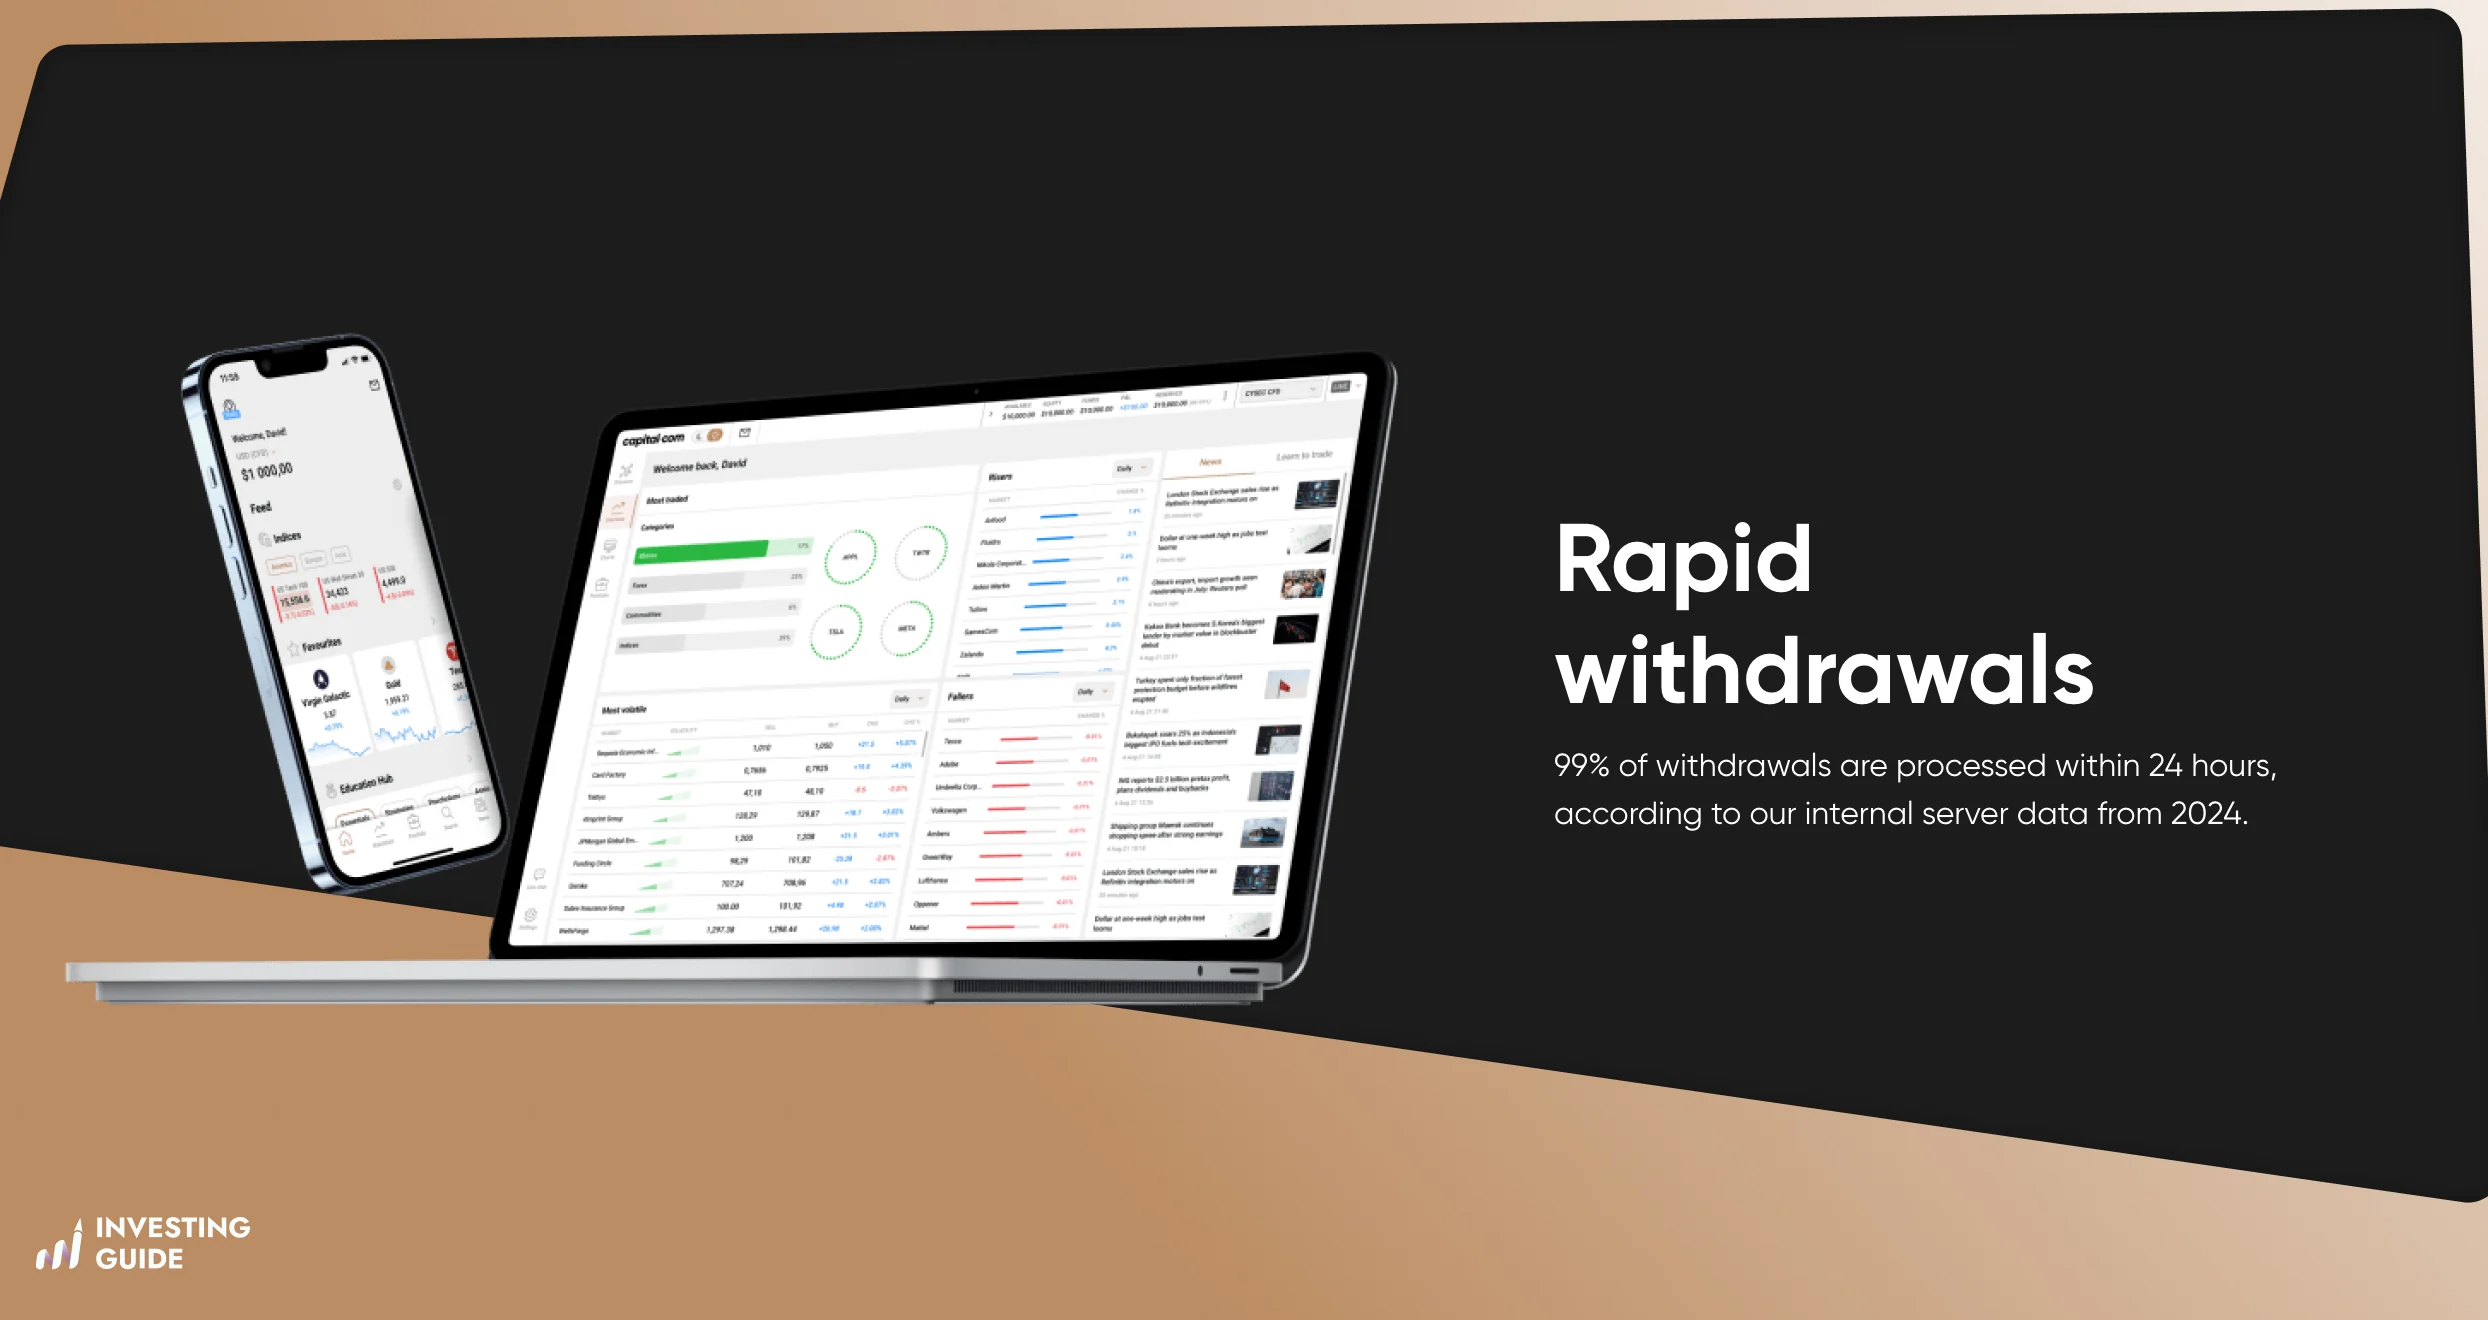
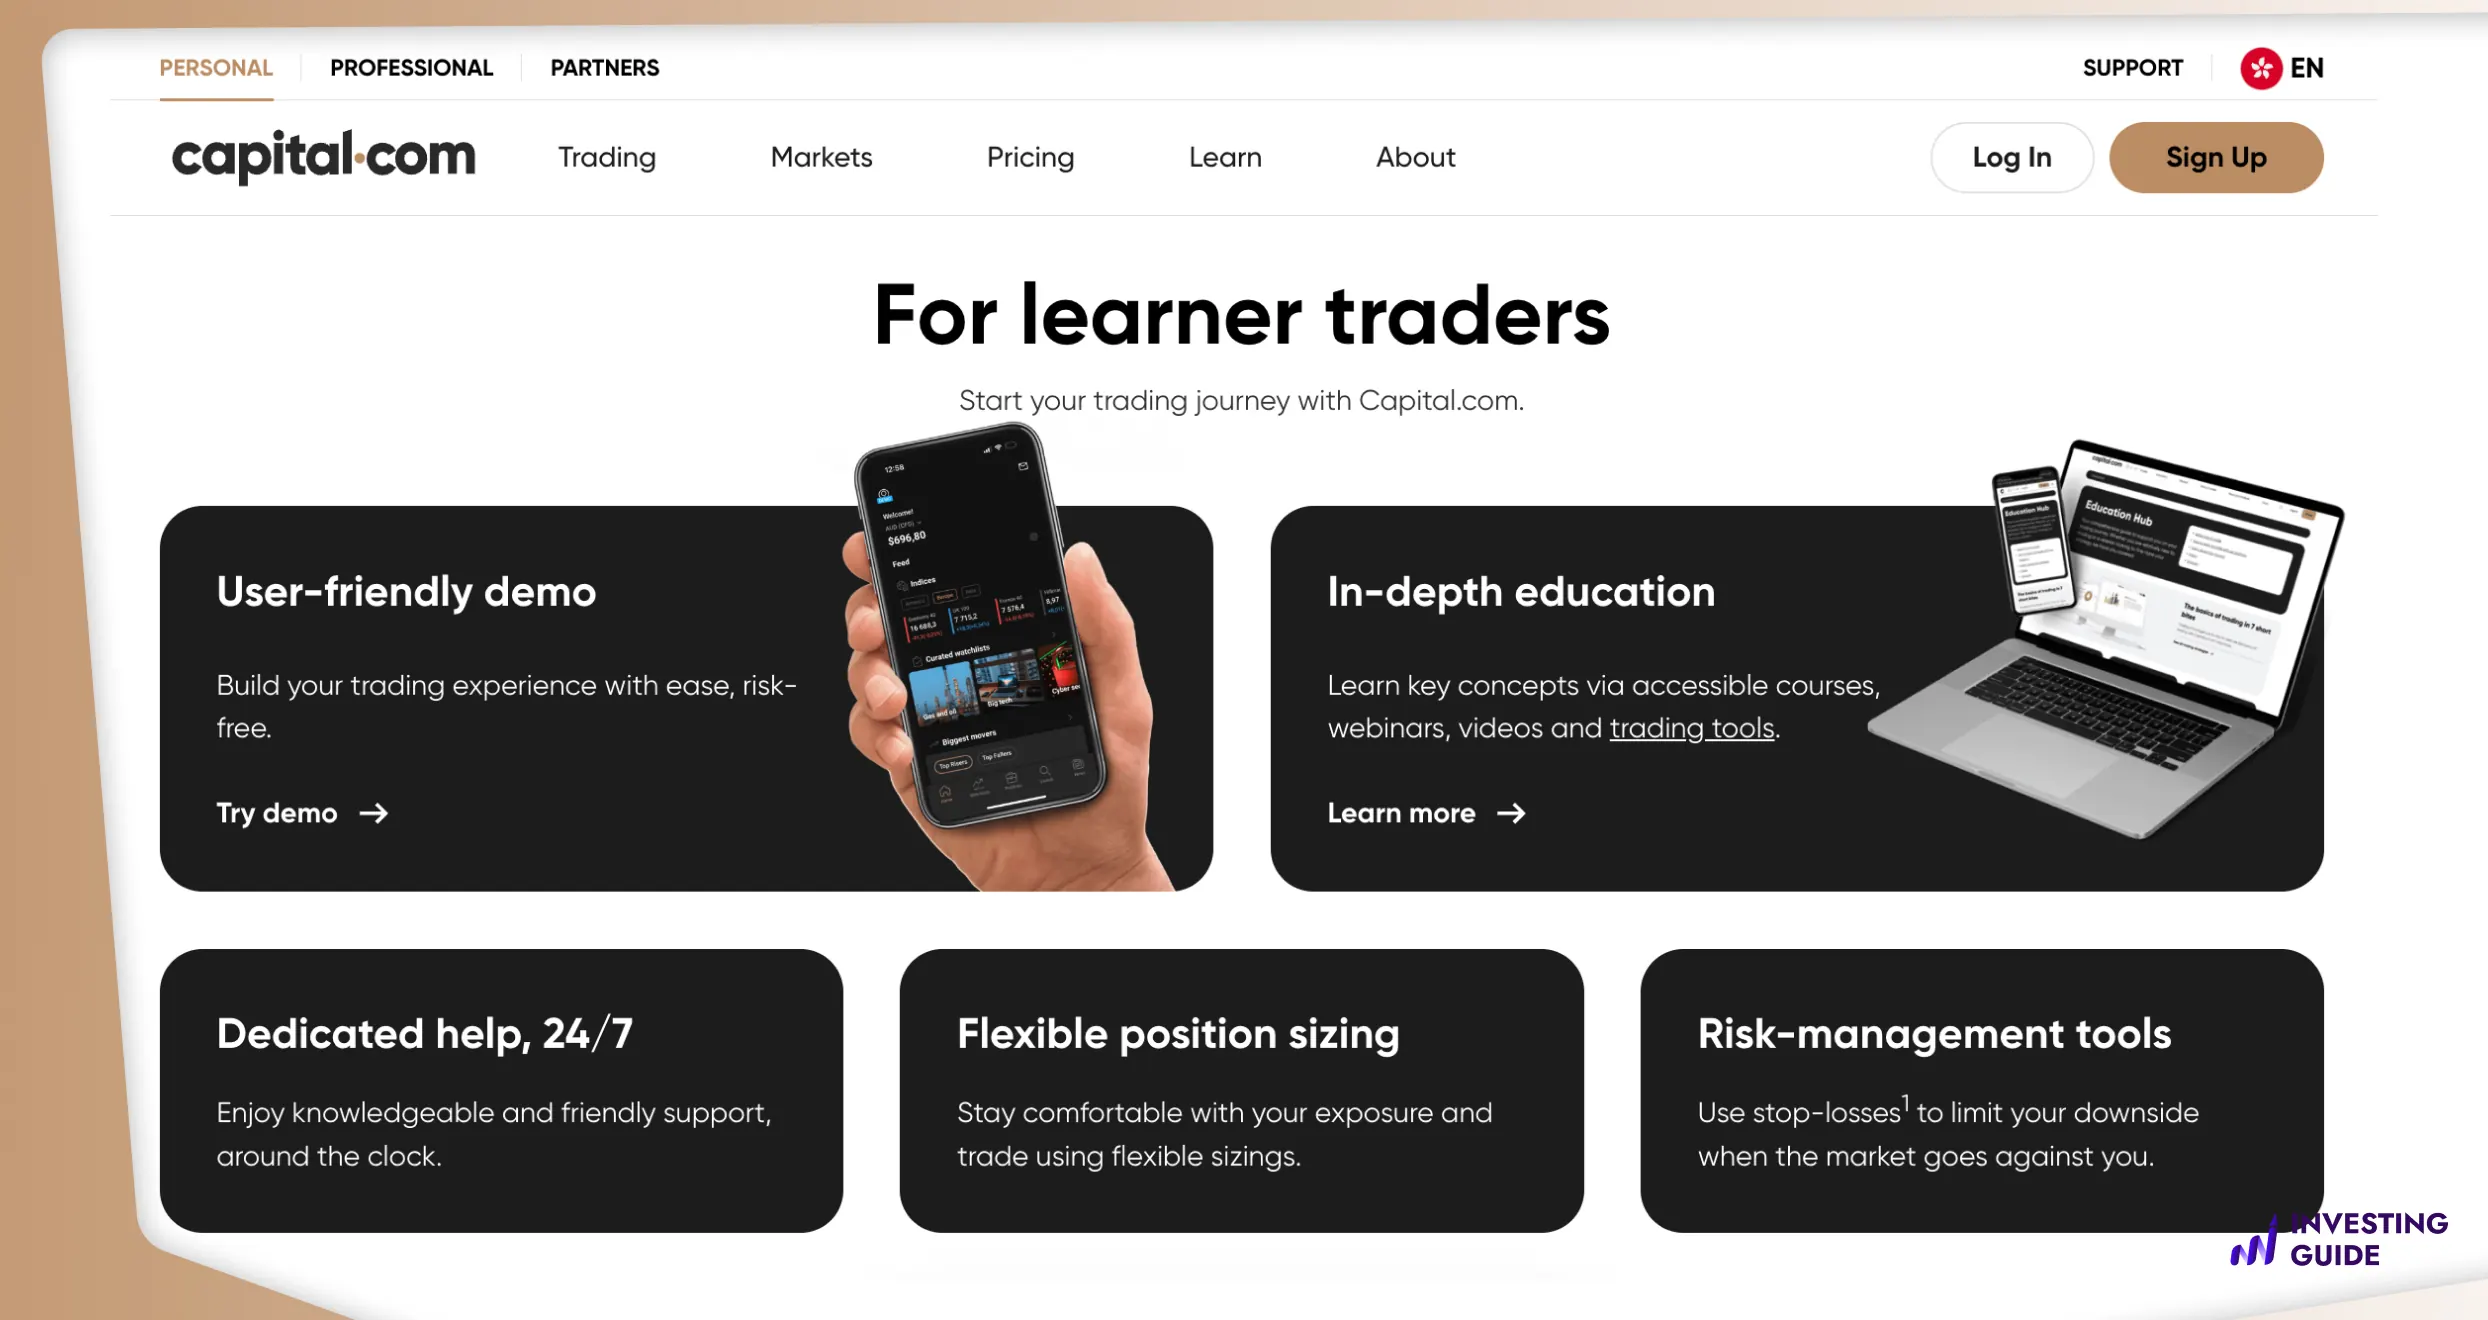
Capital.com offers both spot bond CFDs and bond futures CFDs on instruments like US Treasuries, UK Gilts, and German Bunds, letting you go long or short on rate-driven price moves. Minimum deposit is £20, with no withdrawal fees and a £10 monthly charge after inactivity.
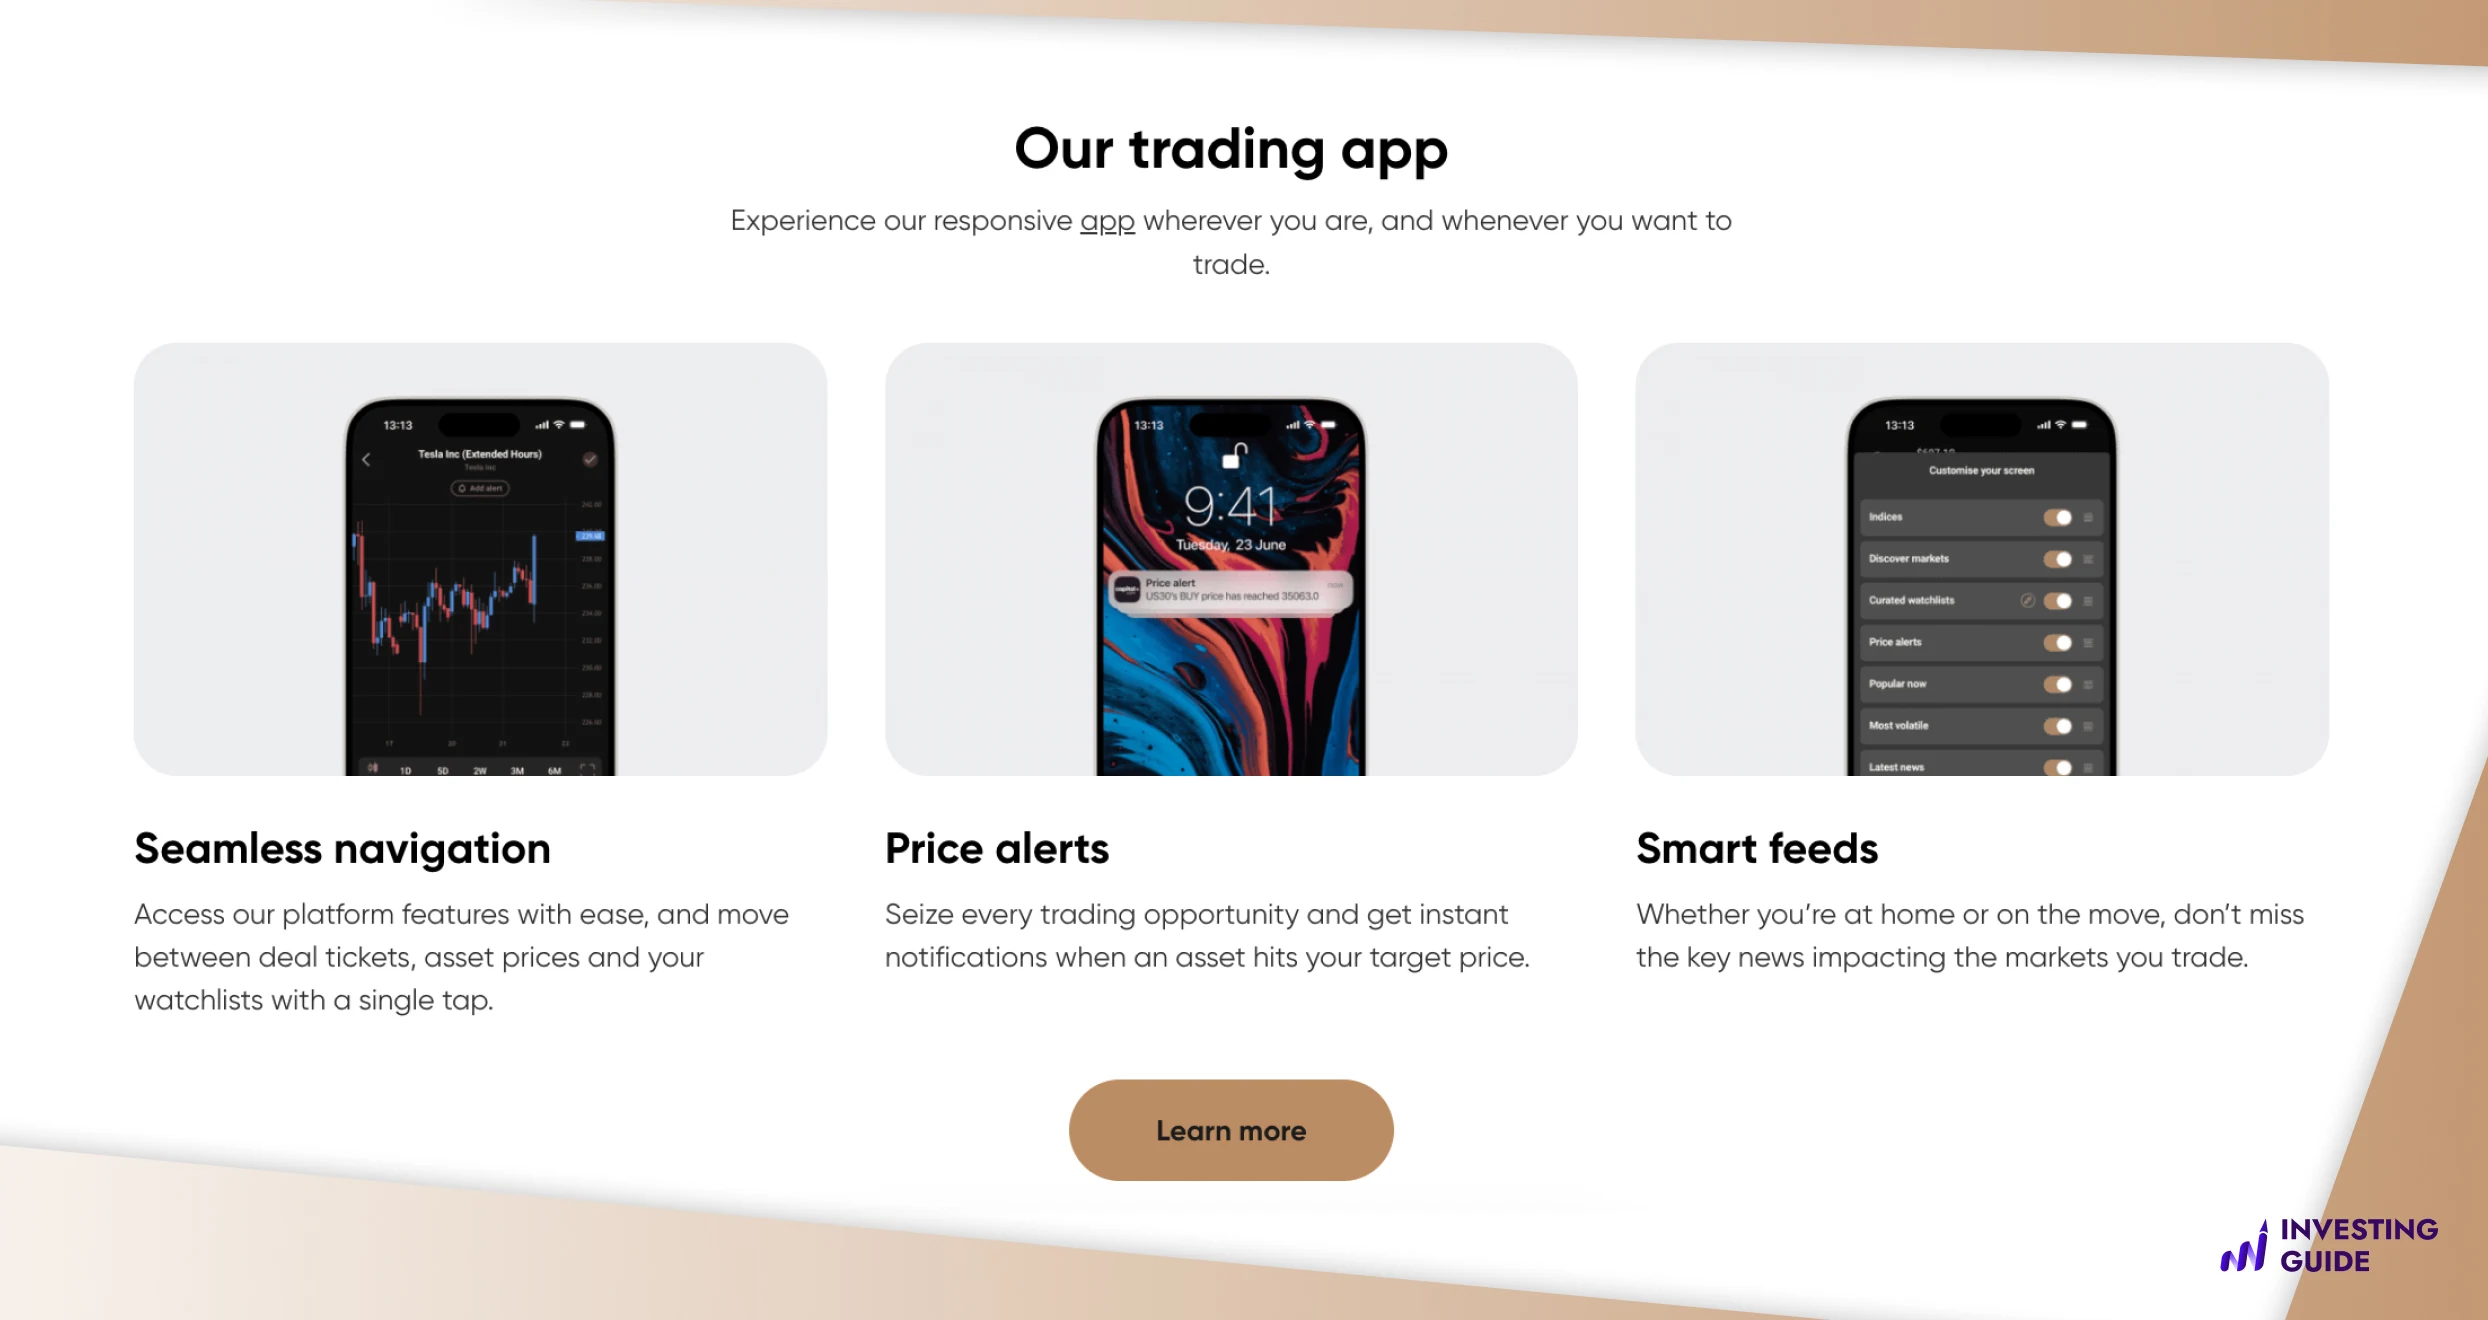
Selected bond markets can also be traded with knock-out options, which apply a predefined cost and built-in risk limit instead of standard margin. Everything is accessed through Capital.com’s web platform or app, alongside its usual charting and alert tools.
Capital.com
✔FCA-regulated
✔24/7 customer support
Pros & Cons
Fees
Trading Assets
Pros
- Both spot and futures bond CFDs available.
- Knock-out options for defined risk limits.
- Low £20 minimum deposit.
Cons
- No direct bond ownership or coupon income.
- No MT5 platform.
| Type | Fee |
|---|---|
| Minimum Deposit | £20 |
| Commission/Spreads | Free commissions, with Capital.com spreads from 0.0006 pips |
| Overnight Funding | Yes, except for the 1X account |
| Currency Conversions | £0 |
| Guaranteed Stop-Loss Orders | Yes |
| Inactivity | £10 per month after 12 months of inactivity |
| Deposits and Withdrawals | £0 |
What are Bonds?
A bond is essentially a form of lending, where you provide money to a government or business in exchange for agreed interest payments. At the end of the bond’s term, known as the maturity date, the issuer returns the full amount you originally invested.
Bonds do not give you ownership in the way shares do. Instead, they provide a fixed income, which can help smooth portfolio returns when share prices are volatile. Many long-term investors use them for stability and predictable cash flow.
Types of Bonds
UK investors have several options:
- Government bonds (gilts): Issued by the UK government. Low risk but offers modest yields.
- Corporate bonds: Issued by companies. Higher-rated firms are more reliable; lower-rated ones may pay more but carry greater default risk.
- Index-linked gilts: Adjust interest and principal in line with the Retail Prices Index (RPI) to protect against inflation.
- Green bonds: Fund environmental or sustainable projects. Favoured by investors with ethical objectives.
Beginners often start with gilts or investment-grade corporate bonds, as these carry lower risk than high-yield options.
How do Bonds Work?
If you buy a £1,000 corporate bond with a 3% annual coupon and a five-year term, you will receive £30 a year, usually in two instalments. At maturity, the issuer returns your £1,000.
You can sell a bond before maturity, but its market value may have changed. Prices tend to fall when interest rates rise and increase when rates drop. The issuer’s credit rating also affects the value of a bond on the open market.
Bonds can provide income, diversification, and capital preservation, but they are not risk-free. Inflation, changes in interest rates, and the issuer’s financial health can all influence returns.
How to Trade Bonds UK: Step-by-step Guide
Bond investing is now far easier than it once was. You no longer need a private broker or large sums to begin. Today, most investors can buy bonds online using platforms designed for both beginners and experienced traders.
Step 1: Set a Clear Investment Goal
Step 2: Choose the Right Account
Step 3: Select a Platform or Provider
Step 4: Decide Between Individual Bonds and Bond Funds
Step 5: Check Ratings and Maturity
Step 6: Make the Purchase
Step 7: Review Your Portfolio
Decide what you want your bond investments to achieve. This might be regular income, capital protection in volatile markets, or diversification away from equities. Your choice of bonds should match your goals, time frame, and risk tolerance.
You can buy bonds through a general investment account or a Stocks and Shares ISA, which shelters income and gains from tax. For pension savings, a SIPP (Self-Invested Personal Pension) account allows you to hold bonds alongside other assets.
Pick a platform that offers the type of bonds you want, whether it’s UK gilts, corporate bonds, or bond funds. Popular options include Hargreaves Lansdown, AJ Bell, and Interactive Investor. Compare fees, research tools, and ease of use for a suitable choice.
Individual bonds offer fixed interest and a known repayment amount but carry the risk of the issuer defaulting. Bond funds, including ETFs, spread your money across multiple issuers, reducing single-bond risk but adding management fees and market-driven price swings.
Credit ratings indicate how likely an issuer is to repay its debt. The top rating is AAA, while bonds rated below BBB fall into the high-yield, higher-risk category. Maturity is also important. Shorter-term bonds are generally less affected by interest rate movements, whereas longer-term bonds can offer higher returns but with greater price fluctuations.
Once you’ve chosen, use your platform to buy. Minimum investments vary – individual bonds often require £1,000 or more, while funds usually allow smaller amounts. Check all fees, especially for overseas bonds or managed funds.
Bond values change with interest rates, inflation, and credit ratings. Review holdings at least annually or when market conditions shift. Keeping a mix of maturities and issuers helps manage risk and smooth returns.
Bonds Trading Risks in the UK
Bonds are generally viewed as lower-risk investments, but they are not risk-free. Understanding what drives their prices and how the market operates is essential for making informed decisions.
Where Can You Buy and Sell Bonds?
- Primary market: New bonds are issued here. UK gilts, for example, are often sold through government auctions or directly via broker platforms. Investors buy them at face value and can hold them to maturity or sell earlier.
- Secondary market: Most bond trading takes place after issuance. Investors buy and sell through brokers or online platforms, with prices moving daily in response to market conditions and sentiment.
Bonds are usually less liquid than shares. Some issues, particularly smaller corporate bonds, may trade infrequently, making it harder to sell quickly at a fair price.
What Affects the Price of Bonds?
Several key factors influence the price of a bond:
- Interest rates: Rising rates make existing bonds with lower coupons less attractive, often pushing prices down. When rates fall, prices usually rise.
- Inflation: Higher inflation erodes the purchasing power of fixed income, reducing demand and prices unless the bond is index-linked.
- Credit rating: Bonds from financially strong issuers tend to hold their value. If the issuer’s credit outlook worsens, prices can drop sharply.
- Market demand: In uncertain times, investors often favour safer assets like gilts, which can lift prices even if yields stay flat.
By recognising these factors, investors can better assess potential returns against the risks. Bonds can still offer stability in a portfolio, but only when their risks are clearly understood and managed.
Pros and Cons of Investing in Bonds
Bonds can be a valuable part of a balanced portfolio, especially for investors who prefer steady returns and lower volatility. Like any investment, they offer benefits and carry limitations.
Pros & Cons
Pros
- Stability: Bond prices usually move less than shares, helping to manage risk during market swings.
- Regular income: Many bonds pay fixed interest, often twice a year, which can supplement other sources of income.
- Diversification: Bonds often perform differently to equities, providing balance when stock markets fall.
- Tax efficiency: Holding bonds in a Stocks and Shares ISA shields interest and capital gains from tax.
Cons
- Lower growth potential: Bonds typically return less than shares over the long term.
- Interest rate risk: Rising rates can reduce the value of existing bonds if sold before maturity.
- Credit risk: If the issuer defaults, you could lose part or all of your investment, especially with lower-rated bonds.
- Inflation impact: Fixed payments lose purchasing power when inflation rises, unless the bond is index-linked.
Bonds can work well for those nearing retirement or seeking lower portfolio risk. For younger investors with a focus on growth, they may be better used as one element within a wider investment mix.
FAQs
Is now a good time to invest in bonds in the UK?
Yes. However, your decisions should be based upon your goals and the interest rate outlook. When rates are high or peaking, bond prices may be lower, offering better entry points. As always, timing the market is tricky, so it’s wise to focus on your long-term strategy.
How safe is a bond investment in the UK?
UK government bonds (gilts) are among the safest investments. Corporate bonds carry more risk but offer higher returns. Checking the credit rating and using funds to spread risk can help manage this.
Do I pay tax on bond investments?
Yes, unless you hold them in a tax-efficient account like a Stocks and Shares ISA. Outside of that, interest income may be subject to income tax, and profits from selling bonds could attract capital gains tax.
What’s the difference between bonds and shares?
Bonds are debt. When you buy a bond, you’re lending money and receiving interest. Shares represent ownership in a company, offering potential dividends and price growth, but with more risk. Many investors hold both to balance risk and return.
Conclusion
Investing in bonds is not about chasing rapid gains but about building steady, predictable returns with less volatility than equities. For UK beginners, understanding how bonds work, whether gilts, corporate issues, or bond funds, can help create a balanced portfolio and support long-term financial stability. Before committing, decide what role bonds should play in your strategy. Research the available options, compare platforms, and assess the risks. The right choice can help preserve capital and deliver consistent income, even when markets are unsettled.
Related Articles:


I've dabbled in UK bonds, especially gilts, and honestly they're perfect when you want that steady, predictable income without the stress of watching stock prices bounce around all day.